Following the Illicit Funds
Regulatory Reporting Standards for Crypto Businesses
📅 January 28, 2026

Today, many types of institutions have a key role in protecting the integrity of the financial system—and they must fulfill the same responsibilities as more traditional banks. To achieve this, many crypto businesses must register as money services businesses (MSBs), bringing them into scope of key AML/CFT regulations.
Money moves fast, and financial institutions such as banks and digital asset firms handle millions of transactions every day. While most of these are legitimate, some may be linked to money laundering, fraud, or terrorist financing. That’s where regulatory reporting comes in.
Reporting certain activities and transactions to government authorities is part of protecting the financial system and can help provide critical intelligence that helps law enforcement track illicit financial flows, identify bad actors, and safeguard the integrity of the financial system. For some specific types of accounts, such as foreign bank account reports, customers must file reports too.
Beyond compliance, regulatory reporting builds trust and transparency. It signals to regulators, customers, and investors that a company is operating ethically and responsibly. On the flip side, failing to comply can lead to massive fines, lawsuits, reputational damage, and even criminal charges.
This article covers:
Many crypto businesses are subject to the same regulatory requirements as traditional financial institutions, including registration as a Money Services Business (MSB) under FinCEN rules. Companies that convert fiat to crypto, facilitate transfers, or provide custodial wallet services must register by filing FinCEN Form 107, known as the Registration of Money Services Business (RMSB).
💡 Does your crypto business need to register?
| ✅ Yes, if you: | ❌ No, if you: |
|---|---|
| Operate a crypto exchange or payment platform that facilitates crypto-to-fiat conversions | Offer only non-custodial wallets, where users control their own private keys |
| Run a remittance or money transfer service using digital assets | Don’t facilitate financial transactions (e.g., blockchain analytics platforms) |
| Hold customer assets in custodial wallets |
If a business qualifies as a Money Services Business (MSB), compliance with federal regulations is mandatory. MSBs must:
The elements of an AML/CFT program for MSBs are similar to those that apply to banks:
Depending on the state in which they are registered, MSBs also have regulatory obligations imposed at the state level.
Sometimes, transactions just don’t add up. Maybe a customer is moving funds in an unusual pattern, or a brand-new account suddenly starts making large, rapid transfers. When financial institutions spot activity that raises suspicion, they must file a Suspicious Activity Report (SAR) with the Financial Crimes Enforcement Network (FinCEN).
💡 What could trigger a SAR?
SARs aren’t filed for every unusual transaction, but they’re required when patterns suggest potential illicit activity, such as attempts to obscure the origin of funds, to break the “money trail”, or to hide the real entities or individuals involved in a transaction.
Some of the red flags that may trigger an investigation, which could potentially result in a SAR, include:
🚩 Structuring transactions – Breaking large transactions into smaller ones in an attempt to avoid attracting attention. In crypto, this can involve splitting a large transfer across multiple wallets or exchanges in an attempt to avoid triggering alerts.
🚩 Velocity increases – Sudden and unexplained increases in trading activity (e.g., trading once a week to trading 10 times per week)
🚩 Rapid fund movement – Fast, high-volume transfers between unrelated accounts, including “chain-hopping”, meaning exchanges between different digital assets which can be used in attempts to hide the transaction trail
🚩 Anomalous activity – Activity that doesn’t fit the expected customer profile (e.g., a new account immediately making high value transactions, whereas during onboarding they stated an intention to make infrequent low volume transactions, or fiat-to-crypto or crypto-to-fiat exchanges without a clear purpose)
🚩 Use of multiple accounts or exchanges to obfuscate ownership – Customers creating multiple accounts across different exchanges and transferring assets between them in a pattern inconsistent with legitimate trading
🚩 Rapid inflows and outflows of funds – A sudden influx of crypto into an exchange wallet followed by immediate withdrawals to multiple external wallets, which may indicate layering in a money laundering scheme
🚩 High-volume transactions across multiple jurisdictions – Crypto transactions moving through jurisdictions with high risk of illicit finance, such as those with lack of transparency, weak AML/CFT regimes, or sanctions exposure
🚩 Use of privacy coins or mixers – Use of privacy-enhancing assets such as Monero (XMR) or mixers such as Mixero, Tumbler.io, or Tornado Cash, which may indicate attempts to obscure the transactional trail or ownership of assets
🚩 Interaction with sanctioned entities or blacklisted wallets – Transactions involving wallets associated with sanctioned individuals, darknet markets, or known illicit actors
🚩 Common unknown counterparties – Addresses where the ownership is unknown and which are counterparties for multiple users, especially with high volume or high value activity (e.g. where multiple customers interact with an address that is not a known service such as an exchange, where multiple customer interactions would be expected)
💡 Actions to take
Before filing a SAR, an organization should undertake an internal investigation to identify whether the trigger (“unusual” activity) is actually “suspicious”. It may be that upon more detailed analysis, there is a valid explanation for a transaction and there is no requirement to file a SAR. Alternatively, the investigation may identify further red flags indicating that the activity meets the definition of “suspicious”. Importantly, a customer must not be “tipped off” that they are under investigation.
Currency Transaction Reports (CTRs) are mandatory whenever a customer attempts to deposit or withdraw more than $10,000 in cash. Like SARs, CTRs are filed with FinCEN.
The reason for CTRs is that large cash transactions can signal attempts to launder illicit funds or evade detection, especially in cases related to the proceeds of drug trafficking, fraud, or other criminal activity. By monitoring large cash movements, CTRs help authorities track suspicious financial flows and uncover criminal networks.
Crypto businesses registered as MSBs are subject to CTR filing requirements, just like traditional financial institutions. Although most crypto businesses don’t handle cash, there are some that do. One example is a crypto ATM in which fiat cash is exchanged for crypto. Cashing out crypto into cash, or exchanging cash into crypto, both trigger CTR requirements.
💡 What are key considerations relevant to CTRs?
Designation of Exempt Person (DOEP) allows financial institutions to nominate customers as being exempt from CTR filing requirements, provided they meet specific criteria. Like CTR reports, DOEP filings are made with FinCEN.
💡 Who can qualify for DOEP?
At a high level, the following types of customers may meet requirements to be nominated as an “exempt person”:
✅ Banks – To the extent of their domestic operations
✅ Government agencies and publicly traded companies – Includes federal, state, and local government entities
✅ Publicly traded companies and their subsidiaries – Domestic operations of companies listed on the NYSE, American Stock Exchange, and NASDAQ, as well as their majority-owned (51% or more) U.S. subsidiaries
✅ “Non-listed businesses” that meet specified criteria – Domestic operations of U.S. businesses that have maintained a transaction account with the bank for at least two months and regularly engage in cash transactions over $10,000 as part of their legitimate business operations
✅ Payroll customers – Businesses that frequently withdraw cash exclusively for payroll purposes and meet account duration and transaction history requirements
💡 Who does NOT qualify?
The following types of customers may not qualify for DOEP:
❌ Financial institutions – Financial institutions cannot be exempt under the “non-listed” businesses exemption
❌ Certain high-risk businesses, as specified by FinCEN – Including businesses primarily engaged in gambling, pawn brokerage, and other high-risk industries
SAR and CTR: Actions and Outcomes
While SARs and CTRs are both used to detect illicit activity, there are some important differences:
Importantly, the SAR and CTR requirements are parallel but independent. This means that a CTR is not an alternative to a SAR. A SAR must be filed for anything suspicious, even if a CTR has also been filed for that transaction.
In addition to fulfilling the regulatory requirements for filing SARs and CTRs, organizations can also take additional actions including:
Fulfilling the regulatory requirements to file SARs and CTRs not only ensures that an organization remains compliant, it also makes a critical contribution to providing the information necessary for effective joint action between the public and private sector to protect the integrity of the financial system.
In addition to business-level compliance obligations, some crypto users and companies may also have individual reporting requirements, including Foreign Bank Account Reports (FBARs).
FBARs, also known as FinCEN Form 114, require reporting of non-U.S. financial accounts. FBARs are filed with FinCEN and are designed to assist with identifying and taking action against illicit financial flows.
The requirement to file an FBAR applies to U.S. persons including:
If you’re a U.S. person, including a business or entity, where the aggregate value of your foreign accounts exceeds $10,000 at any time during the year, you’ll need to file an FBAR.
💡 What about crypto?
Right now, U.S. persons are not required to include their holdings in foreign cryptocurrency exchanges or custodial wallets on the FBAR, unless those accounts also contain reportable assets besides digital assets. In December 2020, FinCEN announced plans to update FBAR requirements to include digital assets, though a final decision hasn’t been made.
Crypto businesses should monitor FinCEN’s evolving stance on foreign asset reporting and be prepared for their clients to be subject to reporting requirements in future.
As crypto grows, so does regulatory oversight. From SARs and CTRs to MSB registration and potential FBAR requirements, crypto businesses are now firmly within the scope of financial regulations. Meeting these obligations is not just about compliance—it’s about building trust, ensuring transparency, and safeguarding the integrity of the financial system. By staying ahead of regulatory changes and embracing a proactive compliance approach, crypto businesses can navigate the evolving space with confidence and position themselves for long-term success.
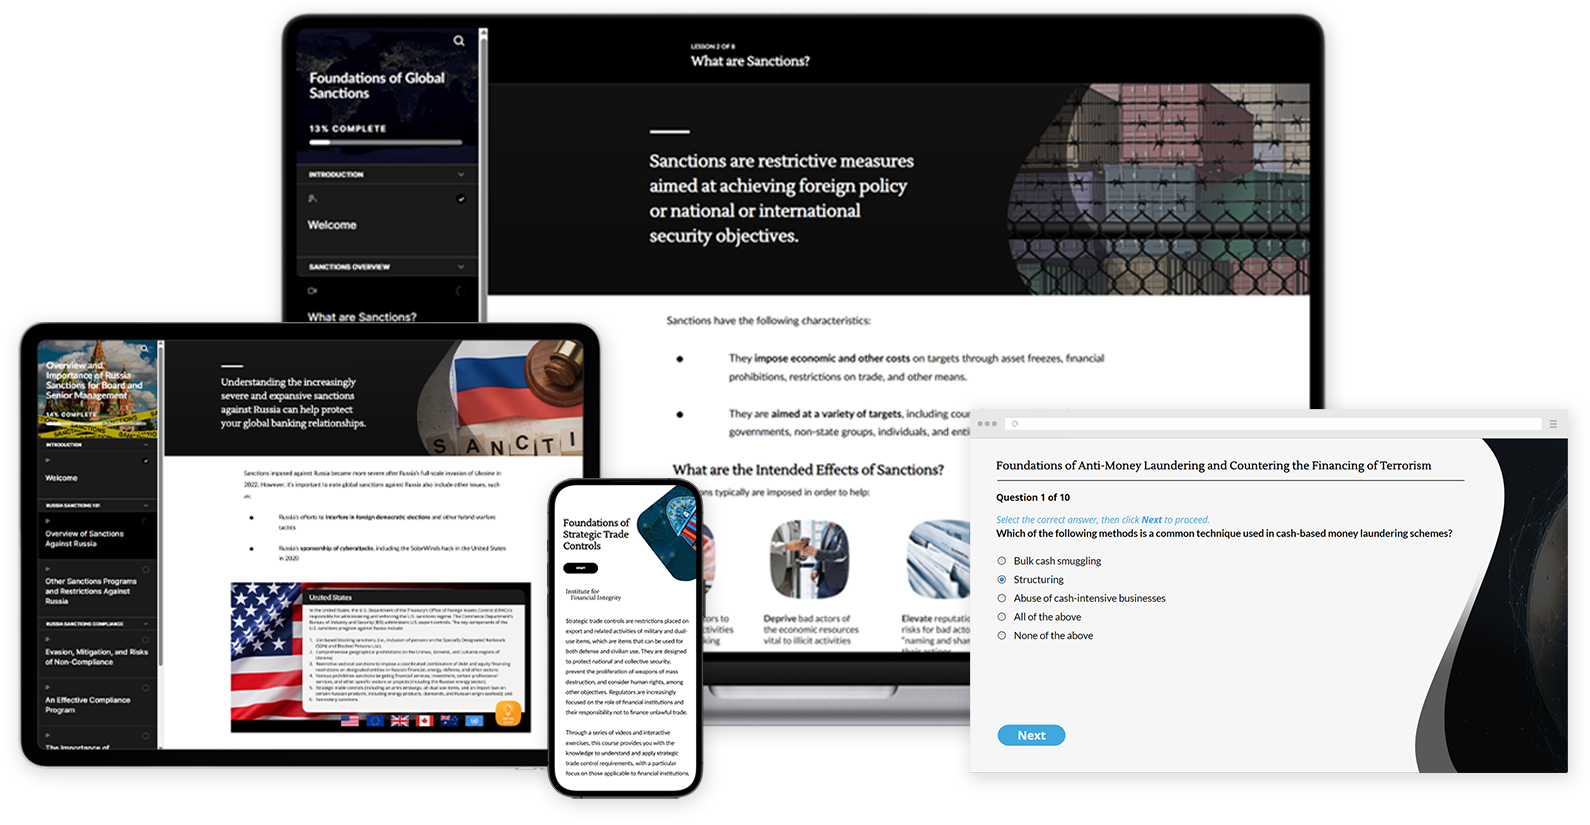
Whether looking to revamp an annual compliance course or to develop a new instructor-led program covering emerging threats, IFI can design, develop and deliver training tailored to your organization’s unique needs.
 https://finintegrity.org/wp-content/uploads/2026/10/bg-expanding-crime.jpg
1357
1800
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-10-14 07:00:092026-10-05 16:11:03The Expanding Scope of Financial Crime Compliance Training
 https://finintegrity.org/wp-content/uploads/2026/10/bg-september-2026-se-report.jpg
1199
1600
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-10-06 07:00:462026-10-05 13:03:02September 2026 Monthly Sanctions and Export Controls Report
 https://finintegrity.org/wp-content/uploads/2026/09/bg-the-data-behind-the-payment.jpg
1140
1800
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-09-30 07:00:312026-09-29 10:35:23The Data Behind the Payment
 https://finintegrity.org/wp-content/uploads/2026/09/real-estate-risk.jpg
614
1000
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-09-17 12:40:222026-09-17 20:35:41Real Estate, Real Risks
 https://finintegrity.org/wp-content/uploads/2026/09/august-2026-se-report-bg.jpg
888
1184
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-09-02 07:00:562026-09-01 13:19:24August Monthly Sanctions and Export Controls Report
 https://finintegrity.org/wp-content/uploads/2026/08/judgement-gap-in-market-abuse-compliance-bg.jpg
841
1500
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-08-25 07:00:462026-08-24 11:34:59The Judgment Gap in Market Abuse Compliance
 https://finintegrity.org/wp-content/uploads/2026/08/oil-pipeline-bg.jpg
1000
1500
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-08-19 07:00:062026-08-19 00:07:14The Illicit Oil Pipeline: How Criminal Networks Turn Crude into Clean Cash
 https://finintegrity.org/wp-content/uploads/2026/08/beyond-the-course-library-bg.jpg
1060
1800
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-08-12 07:00:232026-08-11 12:42:07Beyond the Course Library
 https://finintegrity.org/wp-content/uploads/2026/08/july2026-se-bg.jpg
1177
1800
IFI
https://live-black-pebble.pantheonsite.io/wp-content/uploads/2023/12/GIFI-Placeholder2.png
IFI2026-08-04 07:00:452026-08-04 09:42:02July Monthly Sanctions and Export Controls Report

 January 2026 Monthly Sanctions and Export Controls Report